

Three Clients, Three Kitchens

Senior Vice President, Head of Global Consulting

Key Takeaways
Set yourself apart by understanding what shaped your clients, not just the situation they’re facing today.
Look beyond facts and numbers. The more you understand your client’s money identity, the more their behavior starts to make sense.
Reduce judgment and create psychological safety. Clients are often more receptive to your influence when they feel safe, seen, and understood, not judged.
Every one of your clients has a money story. The most important chapters were often written long before they met you. Understanding them can help you have the kind of conversations few advisors ever do.
What if it’s not about the money?
A professional athlete can earn more before age 30 than most families will see in generations, then be broke a few years after the last contract ends. A client with $4 million can spend weeks debating whether to book the $15,000 cruise they have dreamed about for years.
One appears to spend as though money will never run out. The other has done everything right and still hesitates to enjoy what they built.
On paper, neither behavior makes much sense. Most advisors would start by looking at the money. The money may be new, but the story usually isn’t.
New wealth, old wiring
Your clients bring more than assets to your meetings. They bring the lessons they picked up long before they had a portfolio.
One of your clients grew up hearing money fights from the next room. Another heard “we can’t afford that” so often that wanting something still feels risky. Another never saw money run out, so loss can feel abstract until it happens.
Those early lessons can sit just under the surface for years. But something—an inheritance, a market decline, a major purchase, or a retirement date that suddenly feels real—may bring those lessons to the forefront. And that’s when numbers alone may not be enough.
If your client’s reaction seems bigger than the decision you’re asking them to make, listen for the kitchen-table lesson underneath. What did money teach them to expect? What did it teach them to fear? What did it teach them they were allowed to want?
What if neither one is describing their bank balance?
What if they’re both describing their childhood?
Long before your clients and prospects had portfolios, retirement accounts or financial plans, they had experiences with money. They watched adults argue about it, worry about it, protect it, spend it or take for granted that there would always be more.
Years later, those experiences often show up in the decisions your clients make, the risks they take, the opportunities they avoid, and the questions they still wrestle with.
Why old money lessons stickResearchers sometimes use the term self- schema to describe the mental shortcuts people build about who they are. 1 You don’t need to use that term with your clients, but understanding the concept can be helpful. Your client has a story about money, just as everyone does. They picked it up early, usually by watching what happened around them. Did money start fights? Did it disappear? Did it make people feel safe? Did it prove whether someone had “made it”? Those lessons can stick around long after the client’s life looks different on paper. So when a reaction feels bigger than the decision in front of them, it may be because the decision is touching something older. So if your client’s reaction feels too big for the decision, don’t rush past it. Something about that choice may be hitting an older nerve. |
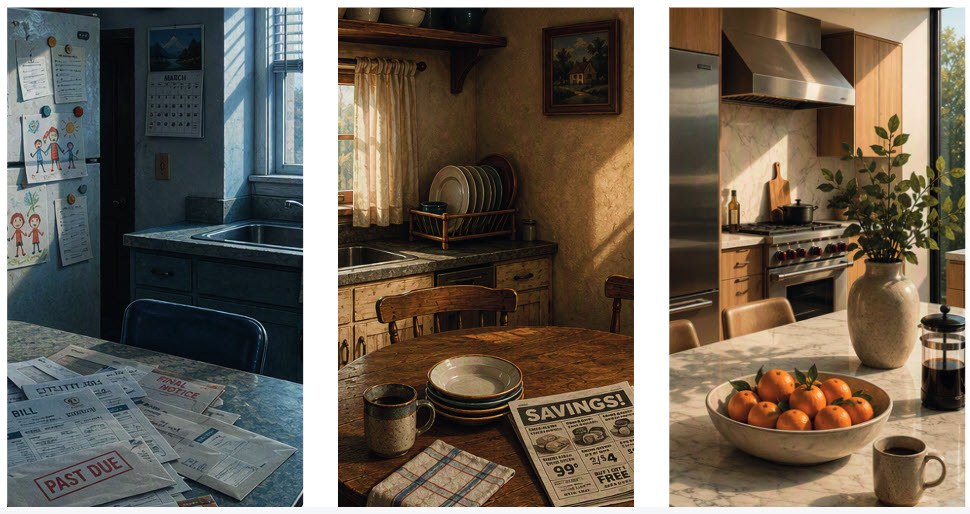
Three kitchens
Most of your clients recognize one of these kitchens. It’s where they learned what money does to people. The challenge is that most people rarely volunteer that information. Sometimes they don’t recognize the connection themselves, or they’re reluctant to revisit it. Often, they worry about how you’ll perceive them.
A simple place to start is to invite them to tell you a story, without pressing for more than they want to share: Tell me a story about what happened around the kitchen table when money came up in your house when you were growing up. Your client’s answer often reveals far more than a discussion about investment preferences, risk tolerance, or spending habits.
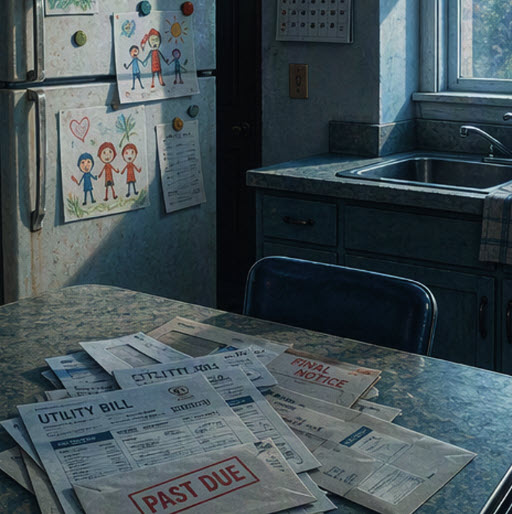
Kitchen #1: PainRaised voices bounce off the cabinets. A stack of unopened bills sits on the counter beside a collection notice no one wants to read. Every time a phone rings, it might be more bad news. Even a simple question about groceries can turn into a fight before dinner is over. This is a kitchen where conversations about money started as discussions and ended in tension or anger. Maybe there was a parent picking up extra shifts and still couldn’t make ends meet. Or a kid who had to wear the same coat two winters running and got bullied at school for it. That kid grows up, and when real money finally lands in their hands, it doesn’t feel like relief. It feels like the reason for every fight that ever happened in that kitchen. Getting rid of it can feel like the fastest way back to normal. This is your client who inherits money and gives half of it away within a year. Or the pro athlete who’s broke two years after their last contract ends. It would be tempting to read this behavior as a lack of discipline or financial literacy. This client may understand the math perfectly well. Their difficulty is what the money represents to them. Try this instead: Start with the story they’re already telling themselves about money and where it began. For many of these clients, money became tangled up with some of the hardest moments of their lives. The circumstances changed years ago, but the feelings can linger. Moving forward may begin with helping them see that they do not have to carry every lesson learned at that kitchen table. Your role is not to diagnose the client. It is to understand the story shaping the decision, then help them consider what keeping, using, or sharing the wealth could make possible now. Conversation starters:
 |
Why the loop can be hard to breakPeople who grow up with a constant awareness of financial limits often carry some of that feeling with them long after their circumstances change. Research has found that financial scarcity can consume mental bandwidth, making concerns about money feel larger and more immediate.² Those concerns can create a predictable pattern in advisor-client relationships. Researchers have observed that people can get stuck in repeating cycles that make perfect sense in the moment. When one person seeks reassurance, the other provides it. Both feel like they’re making progress, yet the same conversation keeps happening.³ For your clients who learned early that resources were limited, those patterns can reinforce one another. The worry shows up, reassurance provides temporary relief, and the cycle begins again the next time a spending decision arises |
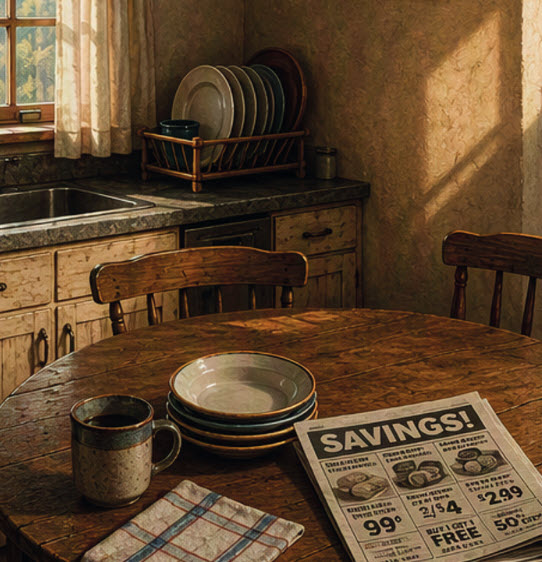
Kitchen #2: ScarcityHere, a coupon organizer lives in a drawer by the refrigerator. A mother pauses before every purchase, silently adding numbers in her head before saying yes. Leftovers are carefully wrapped. Receipts are tucked into a filing folder and saved for months. The thermostat rarely moves. This kitchen is the one advisors overlook the most, because nothing dramatic happened here. The family took a vacation every summer. To Six Flags, maybe. Not Europe. And nobody ever went hungry. But your client heard “we’ll see” a lot, and the unspoken meaning of that phrase was “no”. That kid grows up and becomes the client sitting across from you with four million dollars, asking whether they can really afford a $15,000 cruise. Your client’s brain isn’t stuck in the past. It’s responding to a familiar cue each time money feels tight, even when it isn’t. Try this instead: Step back from the numbers for a moment. Many of these clients have spent years building wealth and making responsible decisions, yet still don’t feel entirely secure. Take time to acknowledge what they’ve accomplished before jumping back into projections and probabilities. Clients like this rarely hear someone point out how much they’ve done right. More often, they hear from advisors when something needs attention. A client who calls before booking the cruise may be asking a bigger question than the one being voiced. For someone who grew up hearing “not now” or “we can’t afford it,” spending can still feel uncomfortable long after the financial constraints are gone. When clients feel understood rather than evaluated, they’re often more willing to share what’s really behind the hesitation. Conversation starters:
 |
Kitchen #3: AbundanceHere, the refrigerator is overflowing with food. If the dishwasher dies, a new one arrives a few days later. Vacations get booked and tuition gets paid. Unexpected expenses are inconveniences, not family conversations. No one here could tell you how much a gallon of milk costs. Money simply appeared. This client grew up without ever seeing an adult hesitate before saying yes. You probably recognize this client. The Opportunity tends to feel familiar, while a meaningful loss can be harder to imagine. Confidence can look a lot like preparedness. Yet this client may have spent little time thinking through what a real loss would feel like because they have rarely had to. Try this instead: Opportunity has worked out pretty well for this client, and that’s part of their story. Give them room to consider outcomes they haven’t spent much time with. What happens if things don’t work out as expected? What changes? What doesn’t? Your conversation may shift once the goals that matter most to them are protected. That foundation gives your client more freedom to pursue opportunities ahead. Conversation starters:
 |
A surprising finding about abundanceGrowing up with money doesn’t necessarily create confidence around money. One study found that people who reported growing up wealthy were likely to report financial dependence, including fear of losing income they had not earned and concern that it could dampen motivation or ambition.4 Abundance can bring its own pressures. Some people may feel more dependent on the money than in command of it |
Set yourself apart
Understanding your clients’ backstory is one thing; recognizing it in a conversation and knowing how to respond are skills you can develop with coaching and practice. Your clients rarely walk into your office and tell you their relationship with money was shaped by something that happened when they were twelve. More often, it shows up in their decisions, questions, and concerns.
Any advisor can compare products or recommend a portfolio. A client’s story only comes from asking, and it’s one of the few things your competitors can’t replicate. The more you listen for it, the easier it becomes to recognize the patterns beneath the surface.
Long before your clients had portfolios, retirement goals, or financial plans, they had a kitchen table.
In many ways, they’re still sitting there.